
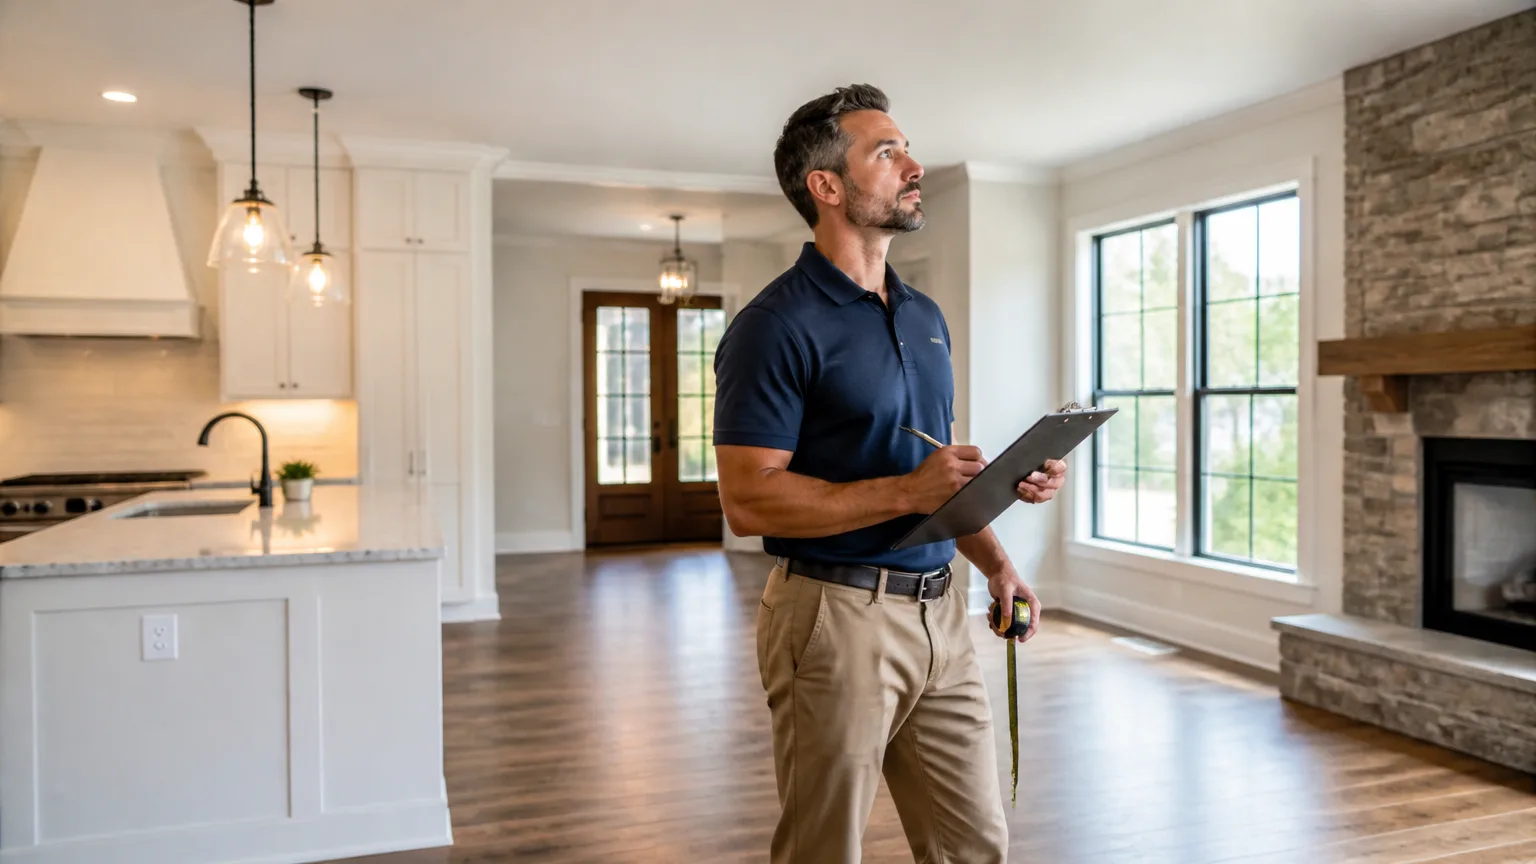
Knowing what do home appraisers look for can help buyers and sellers avoid surprises before closing. A home appraisal estimates the property’s current market value for a lender. The appraiser reviews observable features—such as location, size, condition, upgrades, and functional layout—and compares them with recent sales of similar homes. Personal taste does not determine the result.
The appraisal protects the lender by confirming that the home supports the proposed loan amount. Buyers and sellers can also use the report to anticipate valuation issues, negotiate more effectively, or address concerns before listing or making an offer. If the appraisal comes in below the purchase price, financing and negotiations may change.
An appraisal is not a home inspection. An inspector evaluates systems and defects in detail, while an appraiser focuses on market value. Standards and lender requirements vary by loan type and state, so treat this as a practical nationwide guide, not professional advice. For additional real estate guidance, visit Christopher Garguilo’s Blog.
1. The Home’s Location, Size, and Overall Property Profile
When considering what do home appraisers look for, location provides the starting point. An appraiser studies comparable sales, neighborhood desirability, access to employment and amenities, zoning influences, traffic, and external conditions. Market evidence—not a buyer’s personal preference—determines how location affects value.
The appraiser then records the property’s physical profile, including lot size, usable site features, living area, age, architectural style, parking, and overall condition. The review also considers whether the home’s size and design fit nearby properties. A large lot or distinctive style may add value, but only when local buyers and comparable sales support that conclusion.
Layout matters as well. An appealing floor plan can strengthen marketability, but the appraiser weighs whether it is typical and functional compared with competing homes. Awkward room placement, limited access, or poor use of space may reduce utility despite attractive finishes.
Sellers should gather permits, plans, and other documentation for finished basements, additions, ADUs, garages, and major renovations. Unverified square footage or unpermitted work may not receive full value credit. Buyers should confirm that advertised living area and improvements align with public records and appraisal evidence.
2. Condition, Construction Quality, and Visible Defects
When considering what do home appraisers look for, focus on the property’s condition, construction quality, and visible defects. The review typically includes the foundation, roof, exterior siding, windows, doors, and evidence of poor maintenance. Inside, the appraiser observes plumbing, electrical, heating and cooling systems, interior finishes, water damage, and possible mold indicators.
Appraisers distinguish cosmetic flaws from material defects. Dated paint, worn carpet, or minor scuffs may have limited impact. Structural movement, an active roof leak, unsafe wiring, plumbing failure, significant water intrusion, or conditions affecting habitability can reduce value. Obvious health, safety, structural, or livability concerns may also require repairs under certain loan programs.
An appraisal is not a substitute for a comprehensive home inspection. Buyers should hire an independent inspector to evaluate systems and defects in greater detail, while sellers should address high-impact repairs first. Before listing, start the prep work before listing by improving cleanliness, clearing access to mechanical systems, and correcting safety hazards.
Sellers should retain permits, invoices, and maintenance records. Avoid overspending on purely cosmetic upgrades when unresolved roof, foundation, water, electrical, or mechanical issues could affect marketability more significantly.
3. Upgrades, Features, and Improvements That Add—or Fail to Add—Value
When evaluating what do home appraisers look for, appraisers consider an improvement’s quality, condition, usefulness, and acceptance in the local market. Renovation cost does not automatically equal added value. A remodeled kitchen or bathroom may support a higher opinion of value when comparable homes show similar upgrades and buyers actively seek them.
Luxury finishes, pools, solar panels, and energy-efficient systems require realistic expectations. These features may improve marketability, but they rarely receive dollar-for-dollar credit. A pool may create maintenance and insurance costs, while unusual solar equipment or high-end finishes may appeal to only a limited buyer group. Buyers should compare the feature with neighborhood norms and documented comparable sales.
Sellers should provide a concise improvement sheet listing completion dates, permits, warranties, contractor invoices, and major system replacements. This documentation helps the appraiser verify quality without coaching or applying pressure. Addressing roof, foundation, water, electrical, or mechanical concerns usually matters more than cosmetic spending.
Where appropriate, seller concessions may support negotiations, but they do not replace substantiated property value.
4. Comparable Sales, Market Conditions, and the Final Value Opinion
To determine market value, the appraiser analyzes recently sold, nearby, and reasonably similar homes. These comparable sales, or “comps,” are adjusted for differences in size, condition, location, features, and market timing. Active listings may provide useful context, but they are not completed sales and usually carry less weight.
The appraiser then reconciles the evidence, property observations, and current market conditions into a supported opinion of value. This process explains what do home appraisers look for beyond the home itself: credible market evidence and measurable differences between properties.
An appraisal gap occurs when the valuation falls below the contract price. That result may reduce the lender’s loan amount and require the buyer to contribute more cash. Buyers and sellers should review the contract and consider this response plan:
- At or above the price: Proceed under the contract, subject to remaining lender and inspection requirements.
- Below the price: Explore a price reduction, shared gap, larger down payment, appraisal appeal, or second appraisal. If permitted, the buyer may terminate under the contract’s terms.
- Before responding: Request the appraisal report, verify factual errors, and provide relevant comparable evidence through the lender or agent.
Valuation does not resolve title issues, ownership rights, or legal encumbrances. Review what title insurance covers as a separate, important part of the transaction.
A Practical Appraisal Checklist for Buyers and Sellers
Sellers should disclose known issues, complete high-priority repairs, document improvements, provide reliable access, and price with comparable sales in mind. These steps help clarify what do home appraisers look for, but they cannot guarantee a specific valuation.
Buyers should review the appraisal promptly, compare it with the inspection and contract, and track loan and contingency deadlines. Ask the lender or agent about dispute options if factual errors or relevant comparable sales appear.
An appraisal is one professional opinion within a larger transaction. Equity, financing structure, and market conditions also shape the decision to buy or sell, including how home equity can support a purchase.
Leave a Reply